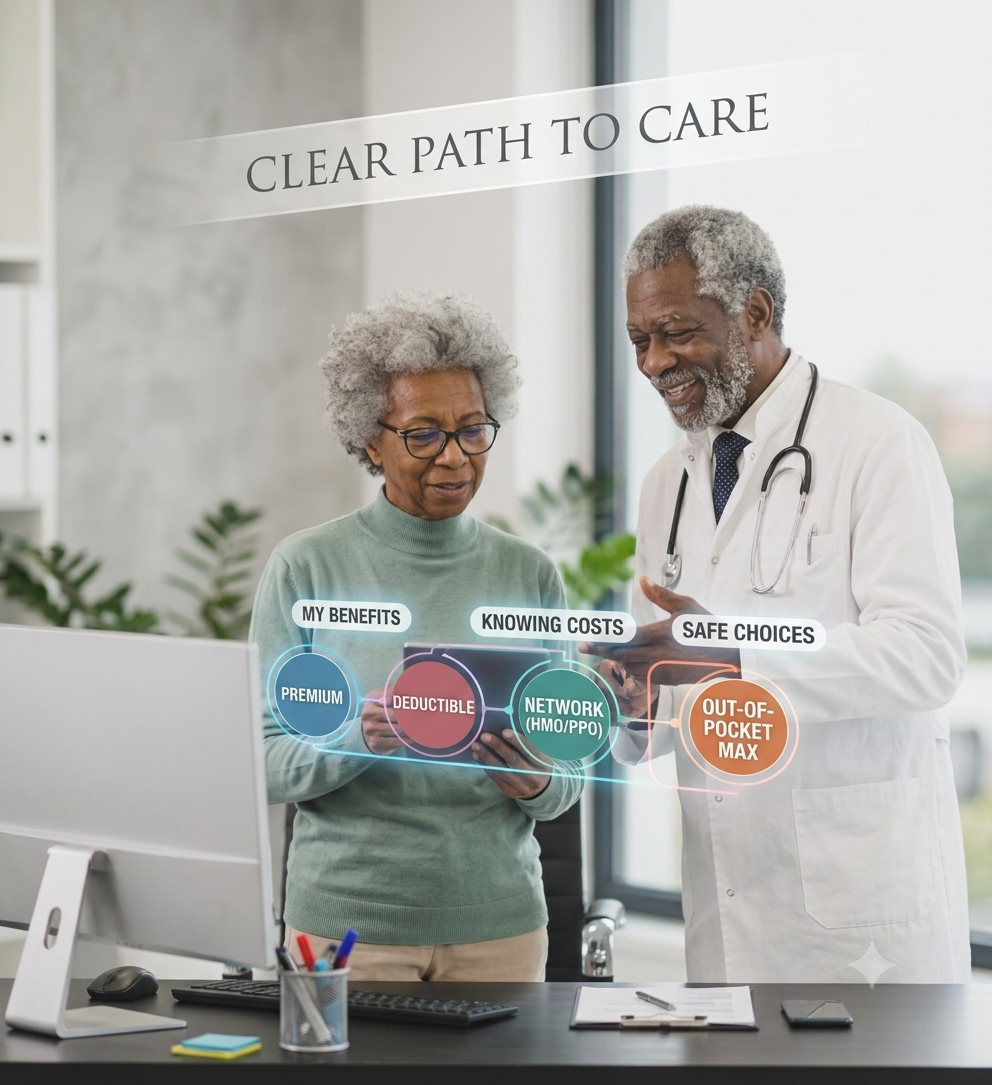
Choosing health insurance can feel overwhelming, especially when you’re trying to understand terms like premium, deductible, copay, coinsurance, provider network, and out-of-pocket maximum.
The good news is that you don’t need to become an insurance expert to make a more informed decision. Once you understand how the major pieces of a health insurance plan work together, comparing your options becomes much easier.
Health insurance helps pay for covered medical care in exchange for a premium. Depending on your plan, you may also pay deductibles, copays, and coinsurance when you receive care. Understanding all of these costs is important when comparing plans.

What Is Health Insurance?
Health insurance is coverage designed to help pay for eligible medical expenses. Depending on the policy, that may include doctor visits, hospital care, prescription medications, preventive care, laboratory services, and other covered health services.
You generally pay a monthly premium to maintain your coverage. When you receive medical care, the amount you pay depends on the rules of your plan.
That’s why comparing health insurance based only on the monthly premium can be misleading. A plan with a lower premium may have a higher deductible or greater cost-sharing when you actually use medical services.
The 5 Costs You Should Understand
Don’t judge a health plan by its monthly premium alone.
How a Deductible and Coinsurance Can Work
Imagine your health insurance plan has a $2,000 deductible and then requires 20% coinsurance for certain covered services.
You may be responsible for covered costs that apply to the deductible until you’ve satisfied that deductible. Afterward, instead of paying the full allowed amount for a covered service, you may pay 20% while the insurance company pays the remaining share, subject to your plan’s specific rules.
What Is a Health Insurance Provider Network?
A provider network is the group of doctors, hospitals, laboratories, pharmacies, and other healthcare providers that have agreements with your health insurance plan.
Using an in-network provider will generally cost less than receiving non-emergency care from an out-of-network provider.
Before enrolling, check whether the doctors, specialists, hospitals, and medications that matter to you are covered by the plan.
HMO vs. PPO vs. EPO vs. POS
You may see several different network structures when comparing health plans. The exact rules vary by plan, so always review the plan documents before enrolling.
HMO
A Health Maintenance Organization generally emphasizes care within its provider network and may require you to choose a primary care provider or obtain referrals for certain specialist care.
PPO
A Preferred Provider Organization generally offers more flexibility to use providers inside or outside the network, although out-of-network care can cost considerably more.
EPO
An Exclusive Provider Organization generally requires you to use in-network providers for covered non-emergency care, subject to the specific rules of the plan.
POS
A Point of Service plan may combine features of HMO and PPO arrangements. Requirements for primary care providers, referrals, and out-of-network services depend on the individual plan.
What Do Bronze, Silver, Gold, and Platinum Mean?
Health Insurance Marketplace plans are grouped into metal categories: Bronze, Silver, Gold, and Platinum.
These categories are about how costs are generally divided between you and the insurance company. They do not indicate the quality of medical care.
| Category | Plan Pays* | You Pay* | General Pattern |
|---|---|---|---|
| Bronze | About 60% | About 40% | Lower premiums, generally higher deductible |
| Silver | About 70% | About 30% | Moderate cost sharing |
| Gold | About 80% | About 20% | Generally higher premium, lower deductible |
| Platinum | About 90% | About 10% | Generally highest premium and lower cost sharing |
*These percentages are general Marketplace estimates for covered services across a plan population, not a promise that every medical bill will be divided according to these percentages.

What Is the Out-of-Pocket Maximum in 2026?
For 2026 Marketplace plans, the annual out-of-pocket limit cannot exceed $10,600 for an individual or $21,200 for a family.
Individual plans may have lower limits.
Your monthly premiums generally do not count toward the out-of-pocket maximum. Costs for services the plan doesn’t cover and certain out-of-network expenses generally don’t count either.
How Do You Choose the Right Health Insurance Plan?
There isn’t one health insurance plan that’s best for everyone. Your goal is to find a plan that makes sense for your expected healthcare needs and budget.
Before You Enroll, Ask These Questions:
- What is the monthly premium?
- What is the annual deductible?
- What are the copays and coinsurance?
- What is the out-of-pocket maximum?
- Are my doctors and hospitals in-network?
- Are my prescriptions covered?
- Do I need referrals to see specialists?
- Is there a separate prescription deductible?
- What would my estimated total yearly cost be based on the care I expect to use?

Don’t Skip the Summary of Benefits and Coverage
One of the most useful documents when comparing health insurance is the Summary of Benefits and Coverage (SBC).
The SBC provides standardized information that can make it easier to compare health plans, including deductibles, cost-sharing, covered services, exclusions, and example coverage scenarios.
Don’t be afraid to compare the SBC documents for two or three plans side by side before making your decision.
Helpful Independent Resources
For official information about Marketplace coverage and health insurance terminology, visit HealthCare.gov’s guide to total health insurance costs .
You can also review the CMS Summary of Benefits and Coverage resources to learn how standardized plan documents can help you compare coverage.
Continue Learning About Insurance
Understanding how different insurance products work can help you make more informed decisions for yourself and your family.
Have Questions About Your Insurance Options?
Understanding insurance doesn’t have to be overwhelming. Explore your options and learn what may make sense for you and your family.
EXPLORE JUST 4 MY FAMILYWhat is the best most affordable health insurance?
The best and most affordable health insurance varies by individual needs and location. Consider researching options through the Health Insurance Marketplace, Medicaid, or short-term health plans. Comparing quotes from multiple insurers like Anthem, Blue Cross Blue Shield, and UnitedHealthcare can also help identify affordable plans. Always evaluate coverage options, premiums, deductibles, and out-of-pocket costs.
How much does a good health insurance plan cost per month?
A good health insurance plan typically costs between $300 to $600 per month for an individual, but this can vary based on factors like age, location, and coverage level.
Is $200 a month a lot for health insurance?
Whether $200 a month is a lot for health insurance depends on various factors, including coverage, location, and individual needs. Generally, it may be considered low for comprehensive coverage but could be reasonable for a high-deductible plan or limited coverage.
What are the 4 types of insurance plans?
Health Insurance
Auto Insurance
Homeowners Insurance
Life Insurance



Leave a Reply