
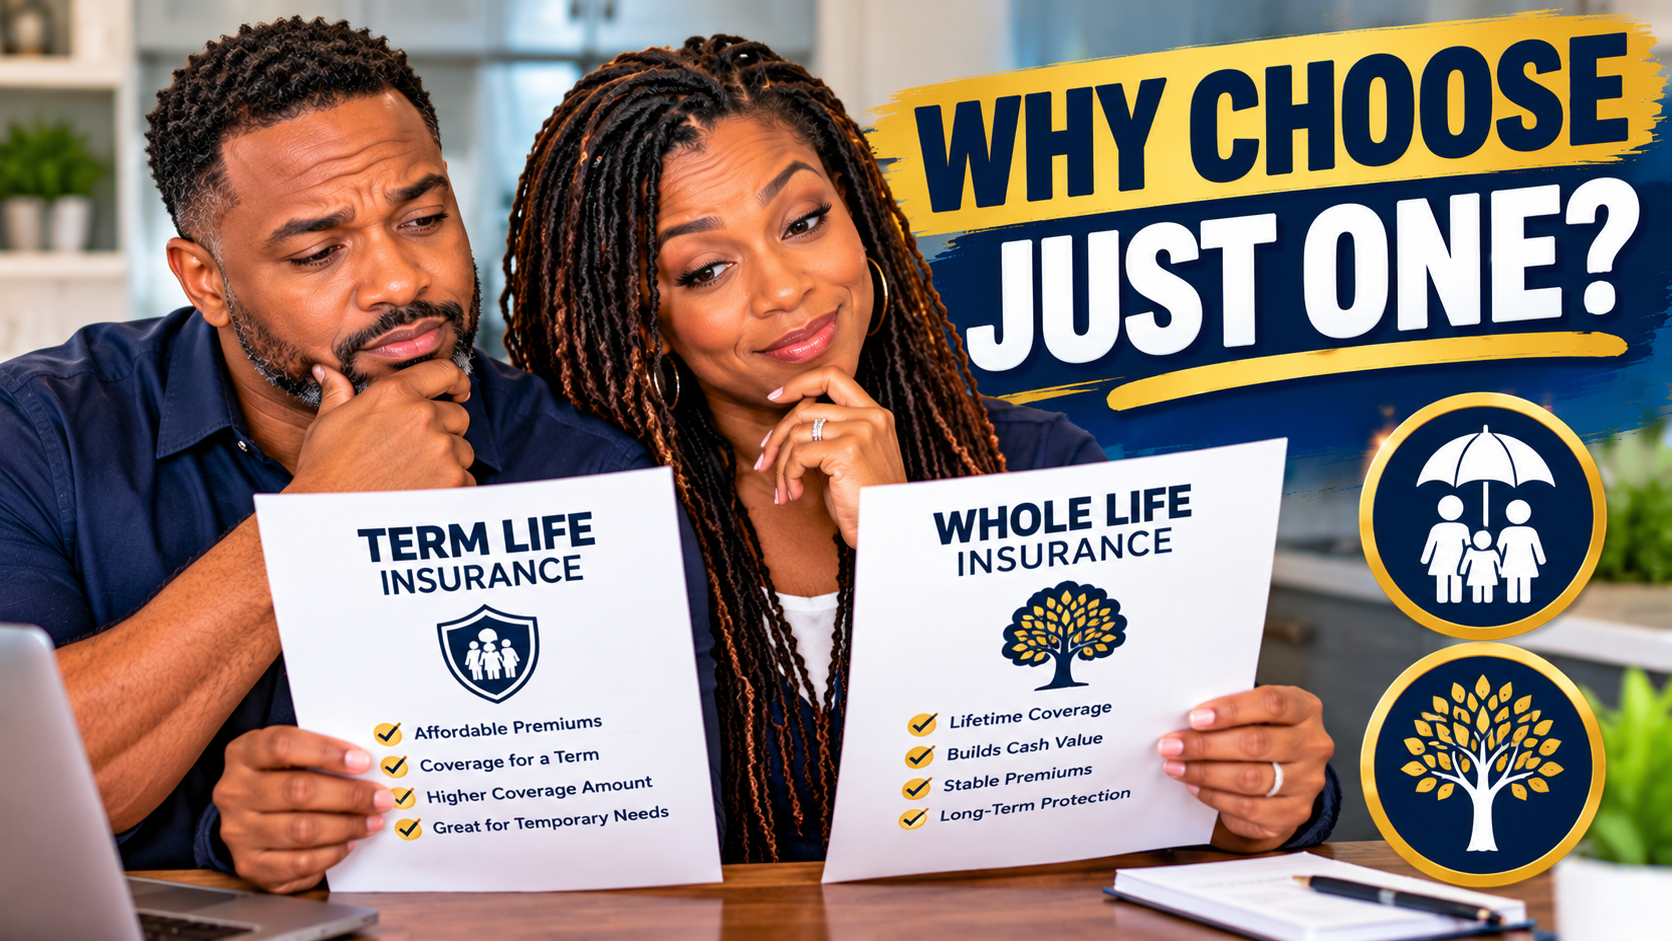
Can you have term life insurance and whole life insurance at the same time?
Absolutely! And for some families, having both may be a practical way to balance affordable coverage today with longer-term financial protection.
Most people assume they have to choose one or the other.
But life insurance isn’t always an either-or decision.
You might want enough coverage to help your family pay the mortgage and replace your income while your children are growing up.
At the same time, you might want a smaller permanent policy designed to remain in place after those temporary financial responsibilities have ended.
That’s where combining term and whole life insurance may make sense.
Let’s break down how it works, what it can cost, and whether it’s worth considering for your family.
Watch: Can You Have Both Term and Whole Life Insurance?
Term life insurance can help address temporary financial needs, while whole life insurance can provide permanent coverage when maintained according to the policy terms.
1. What’s the Difference Between Term and Whole Life Insurance?
Before deciding whether you need both, it helps to understand what each type of policy is designed to do.
Term Life Insurance
Provides coverage for a specific period, often 10, 20, or 30 years. It generally offers a larger death benefit for a lower initial premium than whole life insurance.
Whole Life Insurance
Provides permanent coverage with a cash-value feature. Traditional whole life policies generally have scheduled premiums and guarantees, subject to policy terms.
Term Life Insurance: Protection for a Specific Period
Let’s say you’re 35 years old with two young children and a mortgage.
You might choose a 20- or 30-year term life policy to help protect your family while they’re relying heavily on your income.
If you die while that coverage is active, the policy generally pays the death benefit to your beneficiaries, subject to its terms.
If you outlive the term, the coverage typically ends unless you have and exercise an available renewal or conversion option.
Whole Life Insurance: Coverage Designed to Last
Whole life insurance is a type of permanent life insurance.
It’s designed to remain in force throughout your lifetime, provided required premiums are paid and the policy’s conditions are met.
Whole life insurance also builds cash value over time.
Depending on your policy, you may be able to access some of that value through loans or withdrawals.
But those transactions can have consequences. Loans accumulate interest, and unpaid loans or withdrawals may reduce your death benefit, create tax issues, or cause a policy to lapse.
Remember: Term life focuses on coverage for a defined period. Whole life combines permanent protection with a cash-value component.
2. Why Would Someone Want Both Policies?
Here’s where combining coverage gets interesting.
Different financial responsibilities last for different amounts of time.
Your mortgage might be paid off in 25 years.
Your children may become financially independent long before that.
But certain long-term financial goals or final expenses may still exist later in life.
So instead of purchasing one expensive permanent policy large enough to cover every possible need, some people choose a combination.
They buy a larger term policy for temporary responsibilities and a smaller whole life policy for longer-term protection.
Example: Combining $400,000 of Term Coverage With $50,000 of Whole Life
How Two Policies Could Work Together
Illustrative coverage amounts, not a quote or recommendation.
If the insured person dies during the 20-year term while both policies are active, both policies could pay their respective death benefits, subject to their terms.
If the insured person outlives the term policy and doesn’t renew or convert it, the $400,000 term coverage would end.
The $50,000 whole life policy could remain in force, assuming its requirements continue to be met.
The advantage: You may be able to match larger temporary coverage needs with smaller permanent coverage needs, rather than paying for the same amount of permanent insurance throughout your lifetime.
3. What Are the Benefits of Having Both?
Benefit One: More Coverage During Your Working Years
When your children are young and your family depends on your paycheck, your need for life insurance may be at its highest.
Term insurance can help provide a larger amount of protection during that period.
Benefit Two: Some Coverage Can Remain Later in Life
Once the term policy ends, your permanent policy may still be active.
That can help address long-term goals, provided the coverage amount remains appropriate for your needs.
Benefit Three: You Can Separate Different Financial Goals
Maybe your term policy is intended to replace income or help cover a mortgage.
Meanwhile, your whole life policy may be intended to support a longer-term financial goal.
Having two policies can make it easier to identify which coverage serves which purpose.
Benefit Four: Whole Life May Build Cash Value
Traditional whole life insurance generally builds cash value over time.
However, this benefit comes with higher premiums than comparable term coverage, and accessing the value can affect your policy.
Cash value shouldn’t be treated as free money or assumed to be the best savings strategy for everyone.
4. What Are the Disadvantages of Having Both?
Having two policies isn’t automatically better than having one.
There are several trade-offs to consider.
- Two premiums: You’ll need to budget for both policies.
- Higher total cost: Adding whole life insurance can increase your insurance spending significantly.
- More paperwork: You’ll have separate policy documents, payment schedules, and beneficiary designations.
- Underwriting: Each new policy may require an application and underwriting approval.
- Cash-value complexity: Loans, withdrawals, surrender charges, and tax rules may require additional attention.
Before You Buy Both, Ask Yourself:
Would my family be better protected by purchasing a larger term policy and using the money I save for emergency savings, retirement, or paying down debt?
There isn’t one correct answer for everyone. The best choice depends on your needs, budget, and financial priorities.
5. Can You Have Both Policies From Different Companies?
Yes. You can generally own term and whole life insurance policies from the same insurer or from different companies.
However, insurers may consider how much life insurance you already own when reviewing a new application.
They may evaluate your income, financial obligations, and total requested coverage to determine whether the amount is reasonable under their underwriting guidelines.
You should accurately disclose existing coverage whenever an application asks about it.
And remember: each policy is a separate contract with its own premiums, beneficiaries, exclusions, and claim requirements.
6. Do Both Life Insurance Policies Pay Out?
Generally, yes—if both policies are in force when the insured person dies and the claims meet the terms of each contract.
For example, if someone has:
- $300,000 in active term life insurance
- $100,000 in active whole life insurance
The beneficiaries could potentially receive a combined $400,000 in death benefits.
However, outstanding policy loans, applicable exclusions, or other contract provisions may affect the amounts payable.
Beneficiaries may also differ between policies, so the money won’t necessarily go to the same person.
Helpful tip: Review the beneficiaries on every policy. Marriage, divorce, children, and other life changes may affect whom you want to receive the proceeds.
Term vs. Whole Life vs. Having Both
| Feature | Term Life | Whole Life | Combination |
|---|---|---|---|
| Coverage duration | Specific term | Designed for life | Temporary plus permanent |
| Initial cost | Often lower | Often higher | Depends on both policies |
| Cash value | Usually none | Generally included | In the whole life portion |
| Best suited to | Temporary needs | Long-term needs | Different needs over time |
| Policy management | One contract | One contract | Usually two contracts |
7. Who Might Benefit From Combining Term and Whole Life?
Combining coverage may be worth exploring if you:
- Have children or other dependents who currently rely on your income.
- Want additional coverage while paying off a mortgage.
- Have a long-term reason for maintaining permanent life insurance.
- Can comfortably afford both premiums without neglecting other financial priorities.
- Understand the costs and limitations of whole life insurance.
On the other hand, if your budget is tight and your main goal is protecting your family during your working years, a suitable term life policy alone may be a more affordable option.
8. Questions to Ask Before Buying Both
Before purchasing two policies, ask a licensed insurance professional:
- How much total life insurance do I actually need?
- Which financial responsibilities are temporary, and which may last longer?
- What would the total monthly cost of both policies be?
- What cash-value guarantees and non-guaranteed features apply to the whole life policy?
- Could a convertible term policy meet my needs instead?
- What happens if I can no longer afford both premiums?
- How would each policy pay benefits to my beneficiaries?
Also compare policies from more than one insurer when practical.
For additional consumer guidance, read the National Association of Insurance Commissioners’ life insurance guide.
Frequently Asked Questions
Is it legal to have both term and whole life insurance?
Yes. You can generally own both types of policies at the same time, subject to insurer underwriting requirements.
Can I buy whole life insurance if I already have term insurance?
Yes. You may apply for whole life coverage while keeping your term policy. Approval and pricing depend on the insurer’s underwriting process.
Do I need to cancel my term policy to buy whole life?
No. You don’t generally need to cancel an existing term policy to purchase whole life coverage. Avoid canceling existing insurance until any intended replacement is approved, active, and carefully reviewed.
Can I convert my term life insurance into whole life?
Some term policies include conversion privileges that allow conversion to an eligible permanent policy during a specified period, sometimes without new medical underwriting. Availability, deadlines, and costs vary.
Is having both policies always better?
No. Having both can be useful for some financial goals, but it can also cost substantially more. The right approach depends on your budget, dependents, and coverage needs.
Will my beneficiaries receive money from both policies?
Potentially, yes. If both policies are active and payable when the insured dies, each policy can provide its own death benefit according to its terms and beneficiary designations.
The Bottom Line: You Don’t Always Have to Choose Just One
Term life insurance and whole life insurance serve different purposes.
One can provide a larger amount of coverage for a specific period, while the other is designed to offer longer-term protection and build cash value.
Combining them can make sense when you have both temporary and permanent insurance needs.
But don’t buy two policies just because someone tells you it’s a smart strategy.
Make sure you understand what you’re paying for, how long each policy lasts, and whether the combination fits your family’s financial situation.
The goal isn’t to own the most insurance policies. It’s to have the right protection for the people who depend on you.
Not Sure Whether You Need Term, Whole Life, or Both?
At Just 4 My Family, we help individuals and families explore life insurance options based on their needs and budgets.
Compare your options before deciding what makes sense for your family.
Explore Life Insurance OptionsAnd remember: life happens. Be prepared, stay protected, and always put your family first.
Disclaimer: This article is for general educational purposes and is not individualized insurance, financial, tax, or legal advice. Eligibility, premiums, guarantees, cash values, and benefits depend on the insurer and policy. Review actual policy documents and consult appropriately licensed professionals before making coverage decisions.